How DBP botched Duterte-era contractor loans: lax checks, billions overdue
MANILA, Philippines – Lapses in lending safeguards and years-long delays in collection left the Development Bank of the Philippines (DBP) with more than P4 billion in overdue contractor loans under a program meant to support the Duterte administration’s Build, Build, Build infrastructure drive, state auditors found.
The overdue loans amounted to 61.4% of the P6.67 billion still owed to DBP under the Infrastructure Contractor Support (ICONS) program. Launched in 2017, the program allowed contractors to borrow against expected payments from infrastructure projects, but the Commission on Audit (COA) found cases where loans were released without adequate verification of construction progress.
DBP’s board eventually approved the termination of ICONS on June 3, 2026, citing the high level of overdue loans. The closure, however, still leaves the bank with billions of pesos in debt that it may never recover.
What was ICONS supposed to do?
Launched in 2017, ICONS helped finance contractors undertaking infrastructure projects under the Duterte administration’s Build, Build, Build initiative, including public-private partnership projects.
Contractors need money for construction before they receive full payment from project owners. ICONS helped bridge that gap by lending against expected contract payments, or receivables, assigned to DBP as security.
For that arrangement to work, the bank needed to verify that the projects were progressing and that the payments backing the loans could actually be collected. Under its own lending guidelines, loans were supposed to be released in stages as construction progressed, with account officers required to visit project sites before disbursing funds and continuously monitor borrowers.
But COA found that DBP’s safeguards were not always followed.

A P300-M loan that went wrong
One P300-million loan shows how the ICONS program went wrong, from DBP’s failure to properly check the projects before releasing the money to its struggle to collect from the borrower years later.
In August 2019, DBP approved a P300-million credit line for a contractor undertaking five projects for a government-owned or -controlled corporation (GOCC). The contractor drew the full amount by March 2020, with repayment supposed to come from payments it expected to receive as construction progressed.
On paper, the projects appeared to be well underway. The two biggest projects backing the credit line – each with a contract value of more than P217 million – were reported to be 75.37% and 80.89% complete, respectively.
But DBP released the loans without actually checking how much work had actually been completed. Instead, the bank relied on the value of the contractor’s expected project payments, which covered at least 150% of the outstanding loans.
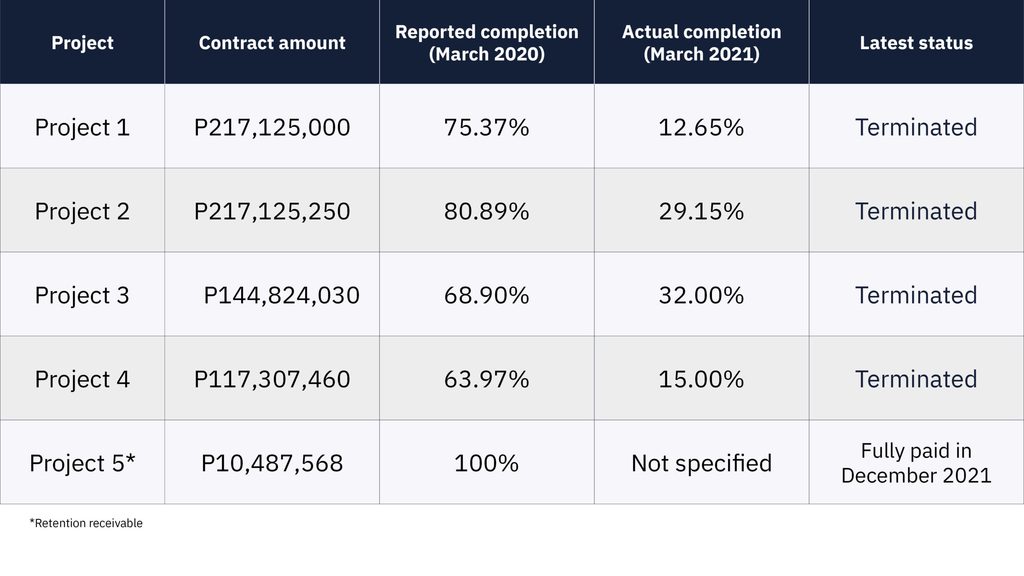
“There was no verification of the actual project accomplishment prior to loan release of the loans, as required by the Circular,” state auditors said in their 2025 report.
By June 2020, just three months after fully drawing its credit line, the contractor had already fallen behind on payments.
It was only in March 2021, a year after the full amount had been released, that DBP checked the actual construction progress with project engineers. The findings revealed substantial discrepancies between the accomplishments the contractor had reported and those subsequently verified.
Two of the projects, Projects 3 and 4, had already been ordered terminated in September 2020 due to construction delays.
“No principal repayment was collected from Borrower 1 despite repeated collection efforts and demand letters, resulting in an outstanding principal balance of P300 million as of December 31, 2025,” the COA said.
By January 2026, the situation had worsened. The GOCC confirmed to COA that four projects had been terminated, while the fifth had been fully paid in December 2021. The government company said it no longer owed the contractor anything from the five projects.
More than five years after the contractor first defaulted, DBP had yet to recover any of the P300-million principal. The bank had already set aside an allowance for the entire amount to account for the expected loss.
Subcontracted work, delayed collections
The P300-million loan was not an isolated case.
Another contractor still owed DBP P490.46 million at the end of 2025, even though the infrastructure projects whose expected payments had been pledged to the bank as security were already completed.
COA found that the contractor had subcontracted most of the work to other companies, leaving it with a financial stake averaging just 3.5% of the projects’ contract costs.
Despite the projects being completed between 2017 and 2021, the contractor continued requesting loan extensions instead of repaying the principal. The audit did not establish what happened to the project payments or why they had not resulted in repayment to DBP.
COA also flagged significant delays in DBP’s efforts to recover overdue loans.
At DBP’s Albay lending center, a borrower defaulted in June 2021, but the first demand notice was sent only by email in July 2025, more than four years later. By the end of 2025, the borrower still owed P97.24 million of its original P100-million loan, with the bank already setting aside provisions for the possibility that the entire remaining amount would never be recovered. The account had also passed through six different officers between 2021 and 2026.
In Tacloban, foreclosure proceedings had yet to begin on a P82.21-million loan that had been overdue since September 2021 because the lending center lacked a full-time lawyer. Its cases were instead being handled by DBP’s Zamboanga legal team.
What has DBP done about the bad loans?
COA recommended investigating possible negligence among bank officers and employees handling ICONS loans, with administrative or legal cases to follow where warranted. It also urged DBP to act faster in recovering unpaid loans, particularly from borrowers still in operation or those with real estate pledged as collateral.
DBP told auditors that its management committee had directed its Legal Services Group to “investigate possible negligence in the credit administration of the loan accounts mentioned.”
But DBP had been looking into some of its largest bad loans for years before it decided to shut down ICONS.
As early as January 19, 2022, the bank’s board had ordered an inquiry into its 20 largest nonperforming loans, including the P300-million ICONS account. Yet it was only on June 3, 2026 – more than four years later – that DBP’s board approved the termination of ICONS.
Meanwhile, DBP’s loan problems extend beyond ICONS. Its gross nonperforming loan (NPL) ratio, which measures the share of loans classified as nonperforming, rose from 7.05% in December 2025 to 9.52% in March 2026, before easing slightly to 9.17% in June, according to data published by the Bangko Sentral ng Pilipinas.
These figures cover DBP’s entire loan portfolio, and it is unclear how much ICONS contributed to the deterioration of the bank’s NPL ratio.
Rappler sought DBP’s comment on how much of the P4.09 billion in overdue ICONS loans it has recovered as of present, what is driving its elevated NPL ratio, and what became of the 2022 inquiry, including why the program was terminated only in 2026.
The bank has yet to formally respond as of press time, although a representative told Rappler that it stood by the explanations it had submitted to COA. This story will be updated if the DBP responds. – Rappler.com