puso diwa foreign
| | | | |

[Puso at Diwa] Foreign currency deposit secrecy: Time for a constitutional rethink

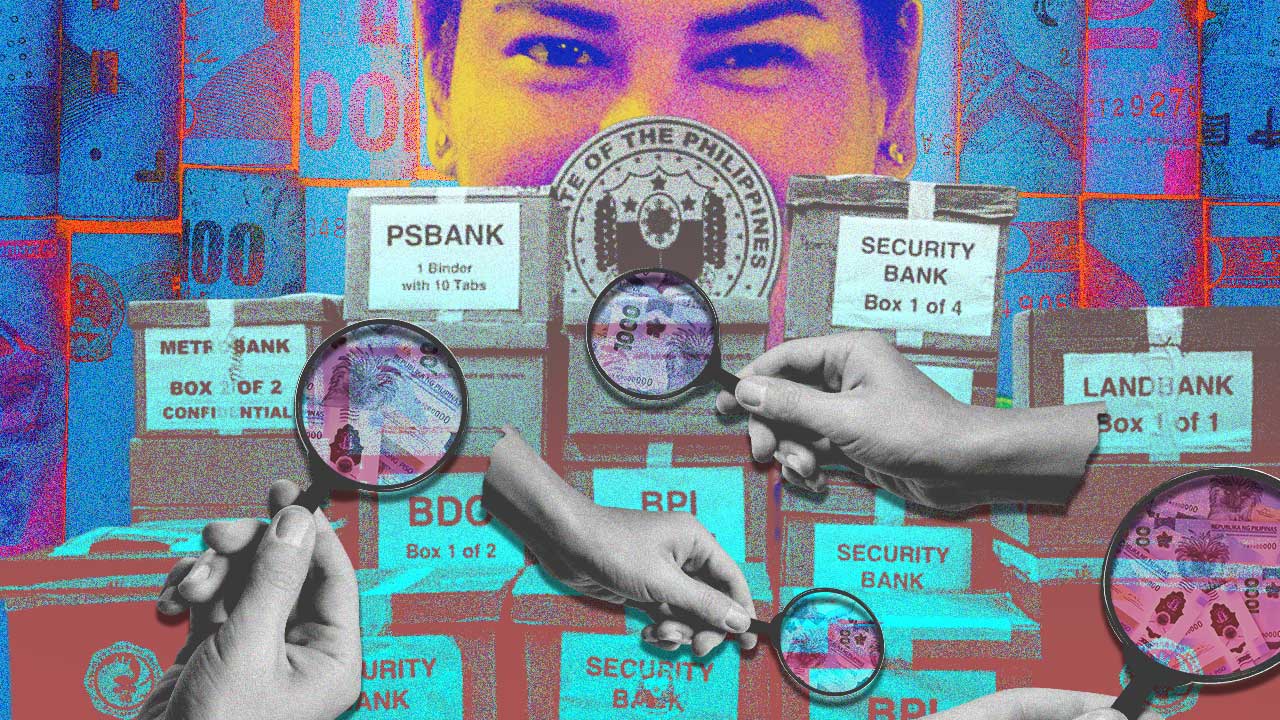
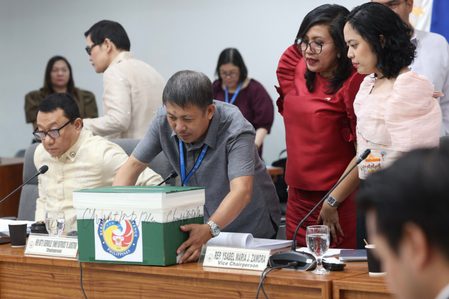
The Senate, sitting as an impeachment court pursuant to the 1987 Constitution, recently granted the prosecution’s request to subpoena a broad range of financial records relating to Vice President Sara Duterte. These include her peso-denominated bank accounts, records from the Anti-Money Laundering Council (AMLC), Bureau of Internal Revenue (BIR) documents, and other financial records involving her husband, lawyer Mans Carpio, and several identified companies and partnerships.

However, the Senate drew the line at the Vice President’s foreign currency deposit (FCDU) accounts. While it authorized access to other financial records, it declined to compel the disclosure of FCDU deposits, citing the strict confidentiality accorded by Republic Act No. 6426, otherwise known as the Foreign Currency Deposit Act.

The ruling highlights an important constitutional question that extends far beyond the present impeachment proceedings: Should statutory bank secrecy prevail when the Constitution requires public accountability from the country’s highest public officials?

Must Read

LIST: Sara Duterte’s bank accounts, AMLC records covered by subpoena request


LIST: Sara Duterte’s bank accounts, AMLC records covered by subpoena request

The Senate’s decision rested on three principal considerations.

First, Republic Act No. 6426 provides exceptional confidentiality for foreign currency deposits. Unlike the Bank Secrecy Law governing peso deposits, the Foreign Currency Deposit Act permits disclosure only upon the written consent of the depositor or under a limited number of statutory exceptions. Impeachment is not expressly included among those exceptions. Existing jurisprudence has consistently upheld this strict confidentiality, and the Senate reasoned that exceptions found under other statutes cannot simply be imported into a special law such as RA 6426.

Second, the senator-judges cited the impeachment of former Chief Justice Renato Corona. During those proceedings, the Supreme Court issued a temporary restraining order (TRO) preventing the Senate impeachment court from compelling the disclosure of Corona’s foreign currency deposits. Although the Court never rendered a definitive ruling on the constitutional issue before the impeachment proceedings ended, the TRO has remained an important point of reference whenever the confidentiality of FCDU accounts is raised.

Third, the Senate adopted a restrained view of its constitutional authority. The senator-judges recognized the broad powers vested in an impeachment court but concluded that these powers should be exercised within the limits of existing statutes unless and until the constitutional relationship between impeachment powers and the Foreign Currency Deposit Act is definitively settled by the courts.

These reasons deserve careful consideration. Yet they do not necessarily settle the constitutional issue.

Much of the jurisprudence cited in legal conversations in support of strict FCDU confidentiality arose from ordinary civil or criminal litigation. Impeachment proceedings are fundamentally different. They are neither criminal prosecutions nor civil suits. Rather, they constitute a unique constitutional mechanism designed to enforce public accountability among the nation’s highest officials.
Must Read

BSP senior official hits bank secrecy limits in Sara Duterte subpoenas


BSP senior official hits bank secrecy limits in Sara Duterte subpoenas

The Corona precedent likewise leaves important questions unanswered. The Supreme Court’s temporary restraining order prevented enforcement during that impeachment trial, but it did not finally resolve whether the Constitution permits an impeachment court to compel disclosure of foreign currency deposits when such disclosure is necessary to determine whether an impeachable offense has been committed. Consequently, no definitive constitutional doctrine currently exists on this precise issue.

This distinction matters. 

The Senate itself acknowledged that the constitutional scope of its authority vis-à-vis RA 6426 has yet to be conclusively determined. By choosing the more conservative interpretation, the impeachment court may have preserved statutory confidentiality, but it may also have limited its own capacity to ascertain the full truth regarding the financial circumstances of a public official whose accountability is directly at issue.

The Anti-Money Laundering Act (AMLA) introduces another dimension to this debate. The AMLA authorizes the examination of bank accounts including, under specified statutory circumstances, foreign currency deposits in connection with money laundering investigations and subject to the legal requirements established by law. Whether these statutory mechanisms may be invoked within the framework of an impeachment proceeding remains a legal question that has not yet been conclusively answered. Nevertheless, they demonstrate that FCDU confidentiality has never been absolute under all circumstances.

A number of respected constitutional scholars support the prosecution panel in that the Constitution itself supplies the stronger legal foundation. They maintain that the Senate’s impeachment authority derives directly from the Constitution and therefore cannot be unduly constrained by ordinary legislation when exercising its solemn duty to determine the truth. Under this view, statutes protecting bank secrecy should not frustrate the constitutional objective of ensuring public accountability.

This is not to suggest that confidentiality laws should be casually disregarded. Foreign currency deposit secrecy has long served an important economic purpose by encouraging the inflow of foreign exchange and strengthening confidence in the Philippine banking system. That public policy remains legitimate and valuable.

But impeachment serves a different and equally compelling constitutional purpose. It exists to protect the integrity of public office and preserve the people’s trust in government. Where these two public interests collide, the legal framework should provide clearer guidance than it presently does.

The present controversy therefore exposes a larger institutional gap rather than merely a disagreement over one subpoena. The uncertainty surrounding the interaction between constitutional impeachment powers and statutory bank secrecy is itself a weakness in the country’s accountability framework.

Must Read

As bank records take center stage in VP impeachment, BPI’s Limcaoco weighs in on bank secrecy laws


As bank records take center stage in VP impeachment, BPI’s Limcaoco weighs in on bank secrecy laws

Whether through legislation or ultimately through constitutional adjudication by the Supreme Court, this unresolved issue deserves definitive clarification. Public officials entrusted with the nation’s highest offices should remain fully accountable under the Constitution, while legitimate expectations of financial privacy should likewise be respected within clearly defined legal boundaries.

The Senate’s recent ruling may have resolved an immediate procedural question. It did not, however, settle the far more important constitutional question. Until that issue is authoritatively resolved, future impeachment courts will likely confront the same dilemma, balancing statutory confidentiality against the Constitution’s enduring commitment to truth, transparency, and public accountability. – Rappler.com

Diwa C. Guinigundo is the former deputy governor for monetary policy and other aspects of central banking. He was a former alternate executive director at the IMF in Washington, DC in 2001-2003. He is the author and editor of several books on political economy, regional crisis and cooperation, debt and economic growth and public policy agenda.

He serves as independent director of several corporate and financial institutions with focus on corporate governance, risk oversight and audit.

He also serves as principal advisor for New York-based GlobalSourcePartners. He remains in the advisory board of ASEAN Macroeconomic Research Office and Singapore Management University’s Sim Kee Boon Institute for Financial Economics.

He is the senior pastor of the Fullness of Christ International Ministries in Mandaluyong.

Below are other Puso at Diwa columns by the author:
Similar Posts

  • | | |

    29 bottled water brands found unsafe in Pakistan

    ISLAMABAD: A quarterly quality assessment of bottled drinking water has found 29 out of 230 brands to be substandard and unsafe for consumption, raising concerns about the quality of commercially available drinking water in Pakistan. The Pakistan Council of Research in Water Resources (PCRWR) conducts quarterly monitoring of bottled and mineral water brands available in the market on the directions of the government. For the latest assessment, samples of 230 bottled and mineral water brands were collected from 20 cities during the April-June 2026 quarter. The samples were analysed in laboratories according to the standards recommended by the Pakistan Standards and Quality Control Authority (PSQCA). Laboratory testing found that several water brands were contaminated with harmful bacteria, making them unsafe for human consumption. A total of 29 brands failed to meet the required quality standards. The report found that nine brands had excessive levels of sodium. These included HR Water Healthy Life, A2Z Pure Bottled Drinking Water, Pure Drinking Water, Deep Blue Pure Drinking Water, Sup Nest Pure Drinking Water, Aab-e-Haram, Aqua Life Bottled Drinking Water, Drinklay and Alpha H2O Bottled Drinking Water. The assessment also found excessive total dissolved solids (TDS) in four brands: A2Z Pure Bottled Drinking Water, Imperial Pure Drinking Water, Aab-e-Haram and Alpha H2O Bottled Drinking Water. The recommended safe limit for TDS is 500 parts per million (ppm). According to the council, 22 brands were found to be contaminated with bacteria. These included My Sial Bottled Drinking Water, JERS Safe Life Bottled Drinking Water, Natural Pure Life, Natural Sup, Al Meer Bottled Drinking Water, Al-Saha Drinking Water, Al-Shifa Pure Life, Royal Fina Bottled Drinking Water, Aqua Nice Pure Life, Noor Aqua, Aqua Pure, Drink Well Pure Drinking Water, Imperial Pure Drinking Water, Zalmi, Deep Blue Pure Drinking Water, Aab-e-Haram, Vital Sup Bottled Drinking Water, Hunza Alter Water, Rehydrate8 Drink Pure Water, Moya Mineral Water, Tynant Aqua Bottled Drinking Water and Aqua Pura Smart. The presence of harmful microorganisms means that the affected brands may pose health risks if consumed without proper treatment. The findings have raised concerns about the monitoring and regulation of bottled water sold across the country. Regular testing is considered important to ensure that drinking water available to consumers meets safety and quality standards. Representatives of some of the companies named in the report, however, rejected the findings. They claimed that their water brands meet the required quality standards.

  • | | | |

    S&P upgrades Pakistan’s rating to ‘B’ o…

    S&P Global Ratings has upgraded Pakistan’s long-term sovereign credit rating from ‘B-’ to ‘B’, citing improvements in economic stability, foreign exchange reserves and reform progress. The global rating agency maintained a stable outlook for Pakistan, indicating expectations that the country’s economic recovery will continue if current policies and reforms remain in place. S&P said the rating upgrade reflects stronger institutional capacity and Pakistan’s progress in implementing reforms under the International Monetary Fund’s (IMF) programme. The agency highlighted that the $7 billion IMF Extended Fund Facility (EFF) has played an important role in improving economic management, supporting fiscal reforms and rebuilding external financial buffers. According to S&P, Pakistan has achieved most of the IMF programme targets so far, which has helped maintain the flow of financial assistance and improve investor confidence. The rating agency also pointed to a major improvement in Pakistan’s foreign exchange reserves. It said reserves increased to around $25.3 billion, including gold holdings, by the end of last month. This is a significant rise compared with the low level of around $6.7 billion recorded in December 2022. S&P said the improved reserve position provides greater capacity to manage external payments and cover upcoming foreign debt obligations. The agency added that continued support from international partners, multilateral institutions and access to global financing markets would help Pakistan strengthen its external position. S&P projected further improvement in Pakistan’s fiscal performance, saying the government deficit could decline to around 4% of GDP by fiscal year 2027. This compares with nearly 8% during the economic difficulties faced in 2022 and 2023. The agency also noted that economic reforms, fiscal discipline and improved financial management could help Pakistan achieve sustainable growth in the coming years. However, S&P warned that a slowdown in reforms, increased fiscal pressures or worsening external conditions could create risks for the country’s future rating. The agency said Pakistan could receive another rating improvement if it continues reducing fiscal deficits, increasing revenues, lowering financing costs and strengthening external economic indicators.

  • | | |

    Private sector lending surges 15% in FY2025–26, …

    Pakistan’s private sector borrowing recorded its strongest growth in four years during the fiscal year 2025–26, signaling renewed business confidence and improving economic activity, according to Adviser to the Finance Minister Khurram Shahzad. Shahzad said private sector credit expanded by nearly 15 percent over the fiscal year, with total lending reaching Rs1.138 trillion. He described the increase as a positive indicator of strengthening economic momentum, driven by greater financial support for businesses and productive sectors. According to the adviser, around 89 percent of the new loans were directed toward key segments of the economy, including manufacturing, wholesale and retail trade, and agriculture. These sectors have played a central role in boosting production, expanding commercial activity, and encouraging private investment. The manufacturing sector emerged as the largest beneficiary, receiving Rs657 billion in fresh financing. Shahzad noted that the substantial flow of credit reflects increased industrial expansion, higher production capacity, and growing confidence among manufacturers. He added that improved access to financing for the trade and agriculture sectors has further strengthened business operations and supported economic growth across the country. Shahzad emphasized that the surge in private sector lending demonstrates rising investor confidence and reflects Pakistan’s continued progress toward greater economic stability, stronger industrial performance, and a more resilient business environment.

  • |

    Pakistan’s total debt burden nears Rs84 trillion as government borrowing rises

    Pakistan’s total government debt stock climbed to a record level of nearly Rs84 trillion by the end of June 2026, highlighting the growing financial burden facing the country amid continued reliance on domestic and external borrowing. According to the latest data released by the State Bank of Pakistan (SBP), the federal government’s total debt increased by 7.4% on a year-on-year basis during the fiscal year ended June 2026. The central government’s debt stood at Rs83,642 billion in June 2026, compared with Rs77,888 billion recorded in June 2025. The debt stock also increased significantly on a monthly basis, rising from Rs81,955 billion in May 2026. The latest figures indicate that the government’s debt increased by around Rs5,754 billion, or Rs5.75 trillion, over the course of the fiscal year. Domestic debt remains major component Domestic borrowing accounted for the largest portion of the government’s total debt. According to SBP data, the federal government’s domestic debt rose by 9.1% year-on-year to Rs59,441 billion by June 2026. The increase reflects continued dependence on the domestic financial market to meet the government’s financing requirements, including budgetary needs and debt-servicing obligations. Meanwhile, the federal government’s external debt increased by 3.3% during the year, reaching Rs24,201 billion by June 2026. Although the growth in external debt remained comparatively lower than domestic borrowing, the foreign-currency component continues to place pressure on the country’s external financing position, particularly when debt repayments coincide with periods of weak foreign exchange inflows. Debt servicing poses growing challenge The continued rise in the debt stock is also raising concerns about the government’s ability to manage debt-servicing costs while creating fiscal space for development spending and public services. A growing share of government revenues is required to meet interest and principal repayment obligations, limiting the resources available for infrastructure, social development and other productive investments. Economic experts have warned that if the debt trajectory is not brought under control, the rising burden could turn into a “debt trap” for the economy. They argue that reducing dependence on borrowing would require stronger revenue mobilisation, greater fiscal discipline, higher exports and sustained economic growth. Improving the efficiency of public spending and reducing reliance on debt-financed expenditures could also help contain the pressure.

Leave a Reply

Your email address will not be published. Required fields are marked *