vantage point pnb
| | | | | | | | |

[Vantage Point] PNB Holdings is going public without asking for public money

When PNB Holdings Corporation (PHC) starts trading on the Philippine Stock Exchange (PSE) on September 25, something unusual will happen. 

There will be no initial public offering or IPO, no new shares sold to investors, and no fresh money entering the company.

Reason: PNB Holdings is listing by way of introduction — a market jargon that is simpler than it sounds.

In an ordinary IPO, a company normally becomes publicly traded and raises capital at the same time. A listing by way of introduction separates those events. 

The shares already exist and are already held by shareholders. Listing merely brings them onto the exchange, so buyers and sellers can trade them.

That is what happened here. The Philippine National Bank (PNB) declared 51% of PHC as a property dividend to PNB shareholders. 

Once those shares become tradable, a shareholder who sells gets the buyer’s money; PHC does not. 

Fresh equity reaches the company only if it later issues new shares through a follow-on offering or another capital-raising transaction.

Late regulatory change

Listing still changes a company profoundly. It creates a visible market price, gives shareholders a route to liquidity, and subjects management to the continuing disclosure, reporting, governance, and public-float disciplines of the PSE. 

It also gives the company a publicly traded equity currency that can later be used for acquisitions or capital raising.

PHC will list 46.9321 billion shares at P1.20, implying a market capitalization of P56.32 billion. Its prospectus says there will be no public offering in connection with the listing.  

An expected secondary private placement by affiliates of LT Group Inc. (LTG) on listing day is not open to the public. 

LTG, founded by billionaire Lucio Tan, is a major publicly listed holding company in the Philippines. PNB serves as its primary banking and major financial subsidiary.

Here is where a late regulatory change matters. When PHC prepared its February prospectus, public ownership stood at about 9.86%. 

Affiliates planned to sell up to 6% to lift the float to at least 15%, while PHC asked for up to three years to reach the then-mandated 20%, possibly through a follow-on offering that could help finance the redevelopment of Makati and Pasay.

That 20% assumption is now stale. Effective August 11, the PSE amended its minimum-public-ownership rule. Companies with market capitalization above P50 billion now have a 15% maintaining public-float requirement, and the rule expressly applies that threshold to listings by way of introduction.

At P56.32 billion, PHC is above the cutoff. Its already approved application predates the amendment, however, and the PSE has not publicly explained how the new filing-time requirement is being handled in this transitional case.

Then comes the more interesting question: what is PNB Holdings worth?

PRIME. PNB Makati Center along Ayala Avenue, Makati City (left) and the PNB Financial Center in Pasay City (right). PNB Holdings Corp. website

Its June accounts carry investment properties at P46.54 billion, but an independent valuer accredited by the Securities and Exchange Commission (SEC) puts their fair value at P85.89 billion: P59.73 billion for PNB Financial Center, P12.83 billion for PNB Makati Center, P13.14 billion for Buendia, and P183 million for other properties. 

The accounting firm Punongbayan & Araullo (P&A) issued a fairness opinion valuing the shares between P1.18 and P1.89. PHC settled on a price of P1.20 per share.

My rough calculation is revealing. Replace the P46.54-billion carrying value with the P85.89-billion appraised value, while leaving the rest of the June balance sheet broadly unchanged, and the adjusted equity comes to about P89.1 billion, or roughly P1.90 a share.

That nearly matches P&A’s upper end. It is not a price target because taxes, liquidity, redevelopment costs, execution risk, and holding-company discounts matter. 

Must Read

[Vantage Point] PNCC’s great puzzle: Why delisting isn’t so simple


[Vantage Point] PNCC’s great puzzle: Why delisting isn’t so simple

Cheap on land, expensive on income

PNB itself carries its retained 49% stake at P25.1 billion after applying a 16.5% marketability discount, implying roughly P51.2 billion for the whole company on that basis.

And this is where the story becomes contradictory. PHC earned only P209.9 million in the first half. Mechanically annualize that, and the P56.32-billion listing value equals roughly 134 times current annualized earnings. PNB Holdings looks cheap on land and expensive on income.

The operating trend is improving. First-half revenue rose 26% to P634.3 million. Earnings Before Interest, Taxes, Depreciation, and Amortization (EBITDA) climbed 40% to P336.5 million and net income jumped 85% to P209.9 million. 

Occupancy rates improved to 90% from 85%. However, the company remains heavily dependent on related parties which generated 54% of total revenue and 51% of rental income and dues, despite their share of rental earnings significantly dropping from 75% the previous year.

The balance sheet gives management room. PHC had P3.025 billion in cash, only P1.12 billion in liabilities, and no interest-bearing debt at end-June. It also had P4.90 billion of contracted future minimum rentals.

Yet, first-half additions to investment properties and equipment were only about P93 million, and the company reported no material capital-expenditure commitments. The big redevelopment spend has not yet arrived.

That is why listing first can make sense. PHC can let the market establish a price, improve the assets, and decide later whether debt, internal cash, partnerships, or fresh equity should finance redevelopment. 

Under the new 15% float rule, a future follow-on offering should no longer be viewed simply as a mechanical journey to the old 20% threshold.

A listed share is not automatically a liquid share, and an appraisal is not cash in the bank. Land must be developed, buildings must earn rent, and management must execute.

But September 25 will give PHC something it has never had before: a daily market verdict.

Most companies arriving on the exchange effectively say: give us your money and we will show you what we can build.

PNB Holdings is reversing the sequence. Here are the properties. Here are the earnings. Here is the balance sheet. You tell us what we are worth. The money can come later.

I welcome your views on these and other issues where decisions made in power shape the country’s economic future. – Rappler.com

Below are some Vantage Point pieces you might have missed:

Click here for other Vantage Point articles.

Similar Posts

  • | | |

    Pakistan’s debt growth falls to 20-year low: Fin…

    ISLAMABAD: Pakistan’s Finance Ministry has reported a significant slowdown in the country’s debt growth, saying the rate of increase fell to its lowest level in two decades during fiscal year 2025-26. According to the ministry, Pakistan’s debt increased by only 7.7 per cent during 2025-26, compared with an average annual growth rate of around 16 per cent over the past 20 years. The ministry said the country’s debt-to-GDP ratio also improved, falling to 68.3 per cent from 75 per cent in fiscal year 2022-23. Between 2019 and 2021, the ratio had remained between 86 and 88 per cent. Pakistan’s external debt-to-GDP ratio also declined to 21.5 per cent, which the ministry described as the lowest level in nine years. The country’s foreign exchange reserves have meanwhile increased substantially, rising from $2.9 billion to $18.4 billion, according to the ministry. The Finance Ministry said Pakistan also repaid Rs4.72 trillion in debt ahead of schedule. It added that annual interest expenditure on government debt declined by nearly Rs2 trillion. The burden of interest payments on government revenue also fell sharply, from 61 per cent to 35 per cent, indicating an improvement in the government’s fiscal position. The ministry further said Pakistan has recorded a primary budget surplus for three consecutive years, reflecting continued efforts to strengthen fiscal management and control expenditure. Pakistan has also returned to international capital markets after a four-year gap. The country’s Panda Bond reportedly attracted demand nearly five times higher than the amount offered, indicating strong investor interest. The ministry also highlighted Pakistan’s improved credit outlook. S&P Global Ratings has maintained Pakistan’s rating at B with a stable outlook, with the ministry describing the current rating as the agency’s highest level for Pakistan in nearly nine years.

  • | | |

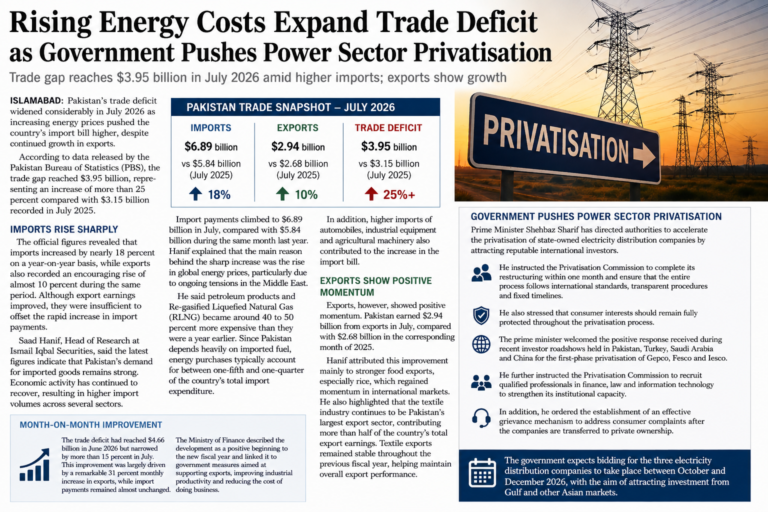
    Rising energy costs expand trade deficit

      Pakistan’s trade deficit widened considerably in July 2026 as increasing energy prices pushed the country’s import bill higher, despite continued growth in exports. According to data released by the Pakistan Bureau of Statistics (PBS), the trade gap reached $3.95 billion, representing an increase of more than 25 percent compared with $3.15 billion recorded in July 2025. The official figures revealed that imports increased by nearly 18 percent on a year-on-year basis, while exports also recorded an encouraging rise of almost 10 percent during the same period. Although export earnings improved, they were insufficient to offset the rapid increase in import payments. Saad Hanif, Head of Research at Ismail Iqbal Securities, said the latest figures indicate that Pakistan’s demand for imported goods remains strong. According to him, economic activity has continued to recover, resulting in higher import volumes across several sectors. He noted that the country’s reliance on imported products has remained significant despite efforts to improve the trade balance. Import payments climbed to $6.89 billion in July, compared with $5.84 billion during the same month last year. Hanif explained that the main reason behind the sharp increase was the rise in global energy prices, particularly due to ongoing tensions in the Middle East. He said petroleum products and Re-gasified Liquefied Natural Gas (RLNG) became around 40 to 50 percent more expensive than they were a year earlier. Since Pakistan depends heavily on imported fuel, energy purchases typically account for between one-fifth and one-quarter of the country’s total import expenditure. In addition, higher imports of automobiles, industrial equipment and agricultural machinery also contributed to the increase in the import bill. Exports, however, showed positive momentum. Pakistan earned $2.94 billion from exports in July, compared with $2.68 billion in the corresponding month of 2025. Hanif attributed this improvement mainly to stronger food exports, especially rice, which regained momentum in international markets. He also highlighted that the textile industry continues to be Pakistan’s largest export sector, contributing more than half of the country’s total export earnings. Textile exports remained stable throughout the previous fiscal year, helping maintain overall export performance. When compared with the previous month, Pakistan’s trade position showed some improvement. The trade deficit had reached $4.66 billion in June 2026 but narrowed by more than 15 percent in July. This improvement was largely driven by a remarkable 31 percent monthly increase in exports, one of the strongest monthly gains recorded in recent years, while import payments remained almost unchanged. The Ministry of Finance described the development as a positive beginning to the new fiscal year and linked it to government measures aimed at supporting exports, improving industrial productivity and reducing the cost of doing business. Meanwhile, Prime Minister Shehbaz Sharif has directed authorities to accelerate the privatisation of state-owned electricity distribution companies by attracting reputable international investors. During a review meeting in Islamabad, he instructed the Privatisation Commission to complete its restructuring within one month and ensure that the entire process follows international standards, transparent procedures and fixed timelines. He also stressed that consumer interests should remain fully protected throughout the privatisation process. The prime minister welcomed the positive response received during recent investor roadshows held in Pakistan, Turkey, Saudi Arabia and China for the first-phase privatisation of Gepco, Fesco and Iesco. He further instructed the Privatisation Commission to recruit qualified professionals in finance, law and information technology to strengthen its institutional capacity. In addition, he ordered the establishment of an effective grievance mechanism to address consumer complaints after the companies are transferred to private ownership. The government expects bidding for the three electricity distribution companies to take place between October and December 2026, with the aim of attracting investment from Gulf and other Asian markets.

Leave a Reply

Your email address will not be published. Required fields are marked *