vantage point not
| | | | | | | | |

[Vantage Point] Why I’m not panicking over Ayala Land

I have been watching Ayala Land’s market decline with more than academic interest.

The stock is down a third this year and more than 40% over the past 12 months. Now comes another indignity: MSCI Inc. is deleting Ayala Land Inc. (ALI) from its Philippines Standard Index at the close of August 31.

MSCI Inc. (formerly Morgan Stanley Capital International) produces global stock indexes used by investors and fund managers as market benchmarks and guides for investment allocation.

There are reasons to worry. But I still see an important distinction between a falling share price and a collapsing business. The numbers tell me Ayala Land is having a difficult year; they do not yet tell me its underlying economic value has deteriorated by anything approaching the market’s punishment.

Start with the damage. First-half revenues fell 10% to P75 billion, while net income dropped 19% to P11.5 billion. Property-development revenues fell 22% to P41 billion and residential revenues declined 15% to P35.3 billion.

But look at the numbers quarter by quarter. ALI earned P5.4 billion in the first quarter (Q1) and P6.1 billion in the second quarter (Q2), a sequential improvement of 13%. That does not amount to a recovery, but earnings are no longer deteriorating quarter after quarter.

Weak spots

Residential demand is still the weak spot. 

First-half reservation sales this year fell 19% to P53.5 billion, while Q2 reservations slipped to P25.6 billion from ₱27.9 billion in Q1. The weakness is hardly ALI’s alone: Philippine Statistics Administration (PSA) data show the value of residential construction nationwide fell 25.8% in June and residential floor area shrank 32.2%, even as non-residential construction value surged 56.4%. I am not declaring that the housing slowdown has bottomed; ALI still has to prove that.

Then there is debt, the intimidating number in the story. 

Total borrowings rose to P337.6 billion at end-June from P318 billion at end-2025, while cash and equivalents stood at P17.4 billion, net gearing at 0.80 times and interest coverage at 4.4 times. The debt mix also became less defensive: 83% was long-term and 60% was fixed-rate, versus 90% and 71% at year-end.

Those numbers deserve attention. But one number changes the debt story: ALI says it had already completed 96% of its 2026 refinancing requirements by June 30, leaving only about P1 billion still to refinance this year.

That is why I refuse to look at P337.6 billion of debt in isolation. ALI does not owe P337.6 billion tomorrow. What matters is when obligations mature: whether the company generates enough cash to service them and whether capital markets remain willing to refinance what comes due. For now, Ayala Land has leverage to manage, not a solvency crisis to survive.

My greater concern is cash generation. ALI raised its 2026 capital expenditure (CAPEX) guidance to P60 billion from P50 billion after spending P39.5 billion in the first half. With reservation sales down 19%, every peso deployed now has to earn its keep. If operating cash flow weakens while investment remains heavy, ALI becomes more dependent on external financing.

There is, however, another piece of the capital story. 

AREIT disclosed a P17.33-billion property-for-share swap involving four malls and two hotels from ALI and subsidiaries. Sponsored by ALI, AREIT is the first and largest Real Estate Investment Trust in the  country, managing a diversified, income-generating portfolio of commercial offices, retail malls, hotels, and industrial land. The transaction would move mature income-producing assets into AREIT in exchange for 462.48 million new shares priced at P37.48 each. It brings no immediate cash, so I would not count it as a solution to ALI’s liquidity problem, but it gives ALI a funding option

Then comes MSCI. Many analysts warned in June that ALI faced a high probability of deletion. On that call, they were right. But predicting index eligibility and determining intrinsic value are different exercises. MSCI tells us ALI’s market capitalization has fallen enough to lose its place; it does not tell us its estates, malls, offices, and hotels have lost a similar proportion of earning power.

What interests me more is what ALI’s parent company, Ayala Corporation, has been doing while the market sells. 

Earning power

On August 14, two days after MSCI announced the deletion, the parent bought another 5.45 million ALI shares at an average P15.411 each, or about P84 million. Reuters subsequently reported another 600,000-share purchase at P15.18. The MSCI battle was already lost, yet Ayala kept buying.

That does not prove the parent is right about valuation. But whatever role index defense may initially have played, purchases after deletion stopped being a mechanical tracking rule and now increasingly looks like a capital-allocation decision.

ALI generated P190.2 billion in revenues and P30.6 billion in core earnings in 2025. Simply annualizing first-half 2026 earnings gives about P23 billion, 25% below last year’s core profit. Yet the stock has fallen more than 40% over 12 months.

That comparison does not prove undervaluation. Markets discount the future, not the past. But it frames the question correctly: has ALI’s long-term earning power deteriorated as much as its market value suggests?

So far, I don’t think so. But ALI must earn my patience quarter by quarter. I want reservation sales to stabilize, operating cash flow to strengthen, leverage contained, and Q2’s sequential earnings improvement sustained. I also want to see whether capital recycling through AREIT reduces funding pressure. History earns credibility; future cash flow earns valuation.

That is why I am not panicking over Ayala Land. The debt is larger, reservations are weaker, and MSCI has delivered its verdict. But refinancing is largely done for the year, Q2 earnings improved sequentially, and the parent is still buying after deletion became inevitable.

The forensic question remains whether the business has permanently lost as much value as the market says it has — or whether fear has simply fallen faster than value.

This analysis is based primarily on Ayala Land and Ayala Corp.’s financial statements, investor presentations and PSE disclosures, supplemented by MSCI index announcements and methodology, AREIT disclosures, and PhilRatings reports. Calculations and interpretations are my own. This column is for informational purposes only and is not intended to influence the market or constitute investment advice or a recommendation to buy, sell, or hold any security.

I welcome your views on these and other issues where decisions made in power shape the country’s economic future.

Below are some Vantage Point pieces you might have missed:

Click here for other Vantage Point articles
Similar Posts

  • |

    IMF-backed move to End EPZ local sales Quota sparks concerns over textile recycling, jobs

    KARACHI: A proposed move to withdraw the permission allowing factories operating in Pakistan’s Export Processing Zones (EPZs) to sell up to 20% of their output in the domestic market has triggered concerns among exporters, investors and international textile-recycling organisations, who fear the policy could disrupt investment, employment and a wider global circular-economy supply chain. The controversy has emerged after Pakistan committed to the International Monetary Fund (IMF) that it would amend the existing rules governing EPZs and prohibit sales from these zones into the domestic tariff area. According to the IMF’s latest programme review, Pakistan has committed to introduce amendments aimed at ending domestic sales by EPZ-based manufacturers. The report states that the amendments were to be placed before the federal cabinet for approval by September 2026. However, exporters and industry representatives have challenged the move, arguing that the existing 80:20 arrangement was part of the investment and regulatory framework under which many businesses established operations in the zones. Under the existing system, EPZ manufacturers can export 80% of their production while selling up to 20% in Pakistan after payment of applicable duties and taxes. Industry stakeholders say the domestic-sale provision is particularly important for products that have limited commercial demand in overseas markets. The proposed abolition has also attracted attention in the United States because American companies supply raw materials and used textiles to Pakistani businesses operating in the EPZs. The US-based Secondary Materials and Recycled Textiles Association (SMART) has approached IMF Mission Chief to Pakistan Iva Petrova, warning that eliminating the domestic-sales provision could have consequences extending beyond Pakistan’s industrial sector. The association has argued that Pakistan occupies an important position in the global textile circular economy, particularly in the sorting, grading, reuse and recycling of used textiles collected in North America and Europe. According to SMART, used clothing and textile materials collected in the United States, Canada and European countries are sent to Pakistan, where they are sorted and graded before being channelled into reuse, recycling, manufacturing and affordable consumer markets. The association has warned that ending the 80:20 mechanism could reduce demand for recovered textiles and place downward pressure on their prices. Such a development, it said, could weaken textile-collection programmes in North America and reduce the income generated by charitable organisations from donated clothing. Organisations including Goodwill, the Salvation Army and St Vincent de Paul depend partly on revenues generated from donated goods to finance a range of social programmes, including workforce training, employment assistance, food support, recovery services, youth programmes and housing assistance. SMART has therefore cautioned that a major disruption in Pakistan’s used-textile market could have financial consequences for charitable organisations in North America, with potential losses running into tens of millions of dollars. The association also warned that reduced demand for used textiles could ultimately result in a greater volume of reusable material being sent to landfills or incinerators rather than being recycled or reused. US exporters raise objections US exporters have also expressed concern over the proposed withdrawal of the 20% domestic-sale allowance. Their concerns are significant because American suppliers form part of the upstream supply chain that feeds Pakistani recycling and manufacturing units located in EPZs. Abid Iqbal, representing Nashmia Industries, said during Express News programme The Review that US exporters had communicated their concerns to Pakistani counterparts. According to Iqbal, US exporters had also been told informally that the IMF itself had not initiated the proposal to remove the 20% quota. The development has consequently raised questions within the industry about how the condition was incorporated into Pakistan’s commitments under the IMF programme and whether sufficient consultation took place with affected stakeholders. Industry representatives have also warned of possible legal and contractual disputes, maintaining that the 20% domestic-sales provision was part of the regulatory and investment framework under which businesses made their investment decisions. They argue that companies entered the zones with an understanding that they would be able to export the bulk of their production while disposing of a limited portion in the domestic market after meeting applicable tax and customs obligations. EPZ rules and proposed amendment The Export Processing Zones Authority (EPZA) operates under the legal framework established through the EPZ Act of 1980. The law enables the establishment of export processing zones with approval from the federal government. Under Rule 228(5) of the Customs Rules, EPZ-based factories have historically been allowed to sell up to 20% of their production in the domestic tariff area, subject to applicable duties and taxes. A higher limit of 30% had been applicable to the Resalpur area. EPZA has reportedly forwarded a proposal to the Federal Board of Revenue (FBR) to eliminate the 20% quota from October 1 in line with the IMF-related commitment. The proposal, however, has exposed differences within the government over the scope and interpretation of the IMF condition. Proceedings of the Senate Standing Committee on Industries held last month indicate that the Ministry of Industries and Production maintained that abolition of the 20% domestic-sales quota was not included in the original IMF agreement. According to the ministry’s position, the initial IMF requirement was restricted to preventing the introduction of new fiscal incentives, including tax concessions and subsidies, rather than immediately eliminating the existing domestic-sales mechanism. The ministry has reportedly argued that the later addition of the quota-related condition requires further clarification. Assessment of EPZs The issue is also linked to an assessment of Special Economic Zones (SEZs) and EPZs that Pakistan was required to undertake under the IMF programme. The government engaged consultancy firm AT Kearney to assess the zones and determine whether their operations were creating distortions in the domestic market. According to records presented before the Senate Standing Committee on Industries, the assessment completed last year concluded that EPZs were not creating significant market distortions. The report, according to the parliamentary proceedings, did not recommend withdrawing existing fiscal incentives. The issue has therefore become a point of discussion between government officials and the IMF as authorities seek to reconcile the lender’s programme requirements with

  • | | | |

    Pakistan, Saudi Arabia eye historic economic partn…

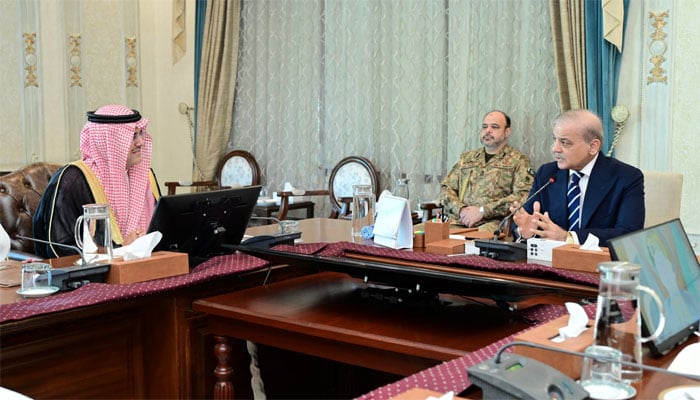
    Prime Minister Shehbaz Sharif has said Pakistan wants to transform its economic relations with Saudi Arabia into a long-term strategic economic partnership. The prime minister made the remarks during a meeting with Prince Mansour, chairman of the Saudi-Pakistan Joint Business Council, who was accompanied by a high-level Saudi business delegation. According to an official statement issued in Islamabad, Prime Minister Shehbaz conveyed his respect and best wishes for Saudi King Salman bin Abdulaziz and Crown Prince Mohammed bin Salman. The meeting focused on expanding economic cooperation and increasing investment between Pakistan and Saudi Arabia. Both sides discussed opportunities for stronger business-to-business and government-to-government collaboration. Prince Mansour expressed interest in investment opportunities in several key sectors of Pakistan’s economy. These included agriculture, ports, highways and the outsourcing of airport operations. The Saudi delegation also showed interest in investment opportunities in real estate, energy, power distribution and information technology. Prime Minister Shehbaz said the time was right to strengthen joint cooperation between the two countries through both government and private-sector partnerships. He stressed the importance of developing stronger economic and commercial ties with Saudi Arabia and creating opportunities for increased investment. Prince Mansour reaffirmed the Saudi government and business community’s interest in expanding commercial links with Pakistan. During their visit, the Saudi business delegation is scheduled to meet senior government officials as well as important representatives of Pakistan’s private sector. The meetings are expected to explore potential investment projects and identify areas where Pakistani and Saudi companies can develop joint ventures.

  • | | | | | |

    ‘Forgotten Island’: Filipino American stories are Filipino stories

    ‘Forgotten Island’ is definitely an achievement worth celebrating, but Filipino storytelling does not begin nor does it end here. We have to take it upon ourselves to add to the narrative and tell the story of the Filipino as we know it.

Leave a Reply

Your email address will not be published. Required fields are marked *