rebalancing msci standard
| | | | | |

Why the rebalancing of the MSCI Standard Philippine Index matters

Global index provider MSCI Inc. (MSCI) is scheduled to rebalance this month its benchmark indicators for the Philippine market, called the MSCI Standard Philippine Index.  

MSCI reviews its indexes regularly to add new stocks, remove underperforming ones, or change company weights to capture and maintain the following vital aspects of the market: accurate market representation, capture real-time market shifts, mitigate risk, ensure high trading liquidity, and align with global index standards.  

In the case of the Philippines, MSCI’s schedule of evaluating stocks for the purpose of rebalancing and index reviews are fixed in the following annual pattern: a) quarterly index review in February; b) semi-annual index review in May; c) quarterly index review in August; d) semi-annual index review in November.

As stated, MSCI will announce the final results of its quarterly index review on August 12, and respectively designated August 31 and September 1 as the implementation and effective date.  

The implementation date is the final deadline when those changes are actually executed in the index calculations. This is important because when MSCI adds, removes, or reweights a stock, passive fund managers have no choice but to purchase newly added stocks and dump deleted stocks. They must align with the new weights to avoid tracking error. This mechanical execution happens entirely by the close of the implementation date. Conversely, the effective date is the immediately preceding trading day.

As a result, the implementation date of rebalancing triggers massive movements of funds that often pushes the price of added stocks upward and drags deleted stocks downward right before the market closes. In some instances, it is said that some a stock’s trading volume can surge five to 10 times from its daily average on its implementation date, or vice versa as the case may be.  

In this connection, active fund managers and arbitrage traders track this event aggressively. They use the multi-week gap between MSCI’s announcement date and the final implementation date to front-run the forced flows, buying early and selling to the passive funds at the implementation close.

Understanding MSCI’s rebalancing process and its buffer zone

MSCI tracks exclusively the large and mid-sized publicly listed companies in the Philippines that represent approximately 85% of the country’s equity universe.  

Specifically, the rebalancing review starts with the taking of sample market data on market capitalization and free float of stocks during the last 10 business days of October, January, April, or July. The result leads to the additions and deletions of stocks for its standard index. This is posted online at 11 pm Central European Summer Time (CEST) on the announcement date. 

At this juncture, index-tracking passive funds must execute all their buys and sells on the implementation date. They do this right before the closing bell to match the new index weights perfectly. 

With the Philippines classified as an “Emerging Market,” MSCI applies specific entry and maintenance metrics tied to its global benchmarks.  

According to the official MSCI Market Classification Framework, the baseline entry requirement size for an “Emerging Market” stock during a review is that the company must comfortably have a minimum market capitalization of US$3.937 billion or P228 billion.  It must also have a minimum “Float Market Capitalization of $1.969 billion or P114 billion. 

Free-float market capitalization is the value of the shares that are truly available to public investors, excluding locked-up blocks held by insiders or governments. 

To remain in the standard index, existing members only need to meet two-thirds of the minimum size requirement. If an existing stock drops below roughly $2.62 billion in full market cap or its float drops significantly below the required levels, it triggers a downgrade to the MSCI Small-Cap Index. 

However, even if a company meets the exact US dollar figures above, it is not automatically guaranteed a slot. MSCI structures the standard index to capture roughly the top 85% of the investable equity universe in the Philippines.  

Conversely, if the country’s total equity pool shrinks significantly during a bear market, MSCI can lower the absolute cut-off size to ensure the 85% coverage threshold is met, preserving the index’s structural continuity.

To prevent a company from being added to the standard index then just to be removed the next month, and then added back again a quarter later because its stock price is hovering above and below the edge of its market size cutoffs, MSCI created a two-tiered boundary, called the buffer zone.  

The lower band of buffer zone is typically placed at two-thirds below the stock’s market size segment cut-off. The upper band is at 1.5 times the stock’s market size segment cutoff.

Again, without the buffer zone, a stock hovering exactly on the cut-off line would constantly cross back and forth due to minor, daily market fluctuations. This would force the index to continuously add and delete the exact same stock. Thus, a stock is generally allowed to remain in the index even if its market capitalization drifts past the official cutoff line, provided it stays within this defined buffer zone. 

Nevertheless, if a stock deteriorates and remains trapped inside a buffer zone for four consecutive semi-annual reviews, MSCI will finally migrate or reclassify it, ensuring the index remains accurate over time without acting on short-term noise.

JFC’s downgrade story and stocks at risk of deletion 

Jollibee Foods Corp. (JFC) was downgraded from the MSCI Philippines Standard Index to the MSCI Philippines Small Cap Index effective June 1, 2026.  The downgrade was specifically driven by the following factors: a sharp drop in its stock price, deteriorating financial fundamentals, and a failure to maintain the float-adjusted market capitalization threshold required for the standard index. (Read column below.)

Must Read

[Vantage Point] The uncomfortable math behind Jollibee’s MSCI demotion


[Vantage Point] The uncomfortable math behind Jollibee’s MSCI demotion

JFC reported in May 2026, a massive 39% year-on-year drop in its first-quarter net income, down to ₱1.47 billion from ₱2.41 billion the previous year — severely missing market expectations.

High global consumer price index (CPI) and rising operational expenses eroded the company’s margins. Likewise, geopolitical tensions in the Middle East raised raw material and logistics costs, squeezing corporate profitability.  

Additionally, the company shifted from a highly visible, cash-generative domestic champion to a heavily leveraged global entity. It went into expensive international acquisitions, which required heavy debt financing. Among those acquired were Smashburger, Tim Ho Wan, and Compose Coffee. But these business decisions raised investors’ concern over the sustainability of the company’s growth strategy.

Before the formal rebalancing, JFC’s stock price had fallen about 27% from its February 2026 peak. This drop pushed its float-adjusted market capitalization to the lower bound of MSCI’s minimum threshold. At the same time, MSCI’s global size requirements for Standard Index inclusion rose. Because JFC fell completely below the protective buffer zone, it triggered an automatic reclassification into the small cap basket. 

The relegation sparked a sharp “technical risk” cycle that negatively affected JFC’s market performance. Multi-billion global funds tracking the MSCI Standard Index were legally required to sell off their JFC holdings. This automatic institutional dumping triggered a 10% single-day stock crash when the news broke.  

Moving to the small-cap segment significantly reduced JFC’s prominence on global screens. Investment houses like First Metro Securities and DBS Bank slashed JFC’s target price from P300 down to P145, citing a “sticky valuation derating” where the stock struggles to trade at a premium multiple. 

To recall, JFC’s free-float market cap stayed comfortably above the standard cutoff, making it a permanent fixture of the MSCI standard index for years. Slowly, JFC’s market cap declined due to market corrections and shifting foreign fund allocations. Because it stayed within the “two-thirds” buffer zone, MSCI left it untouched for several consecutive reviews to give it a chance to recover.

Consequently, JFC’s valuation stayed below the lower maintenance threshold for too long. As prescribed, once a stock breaches the bottom of the buffer zone during an official review period, MSCI is forced to trigger the exclusion mechanism and downgrade it to the small-cap index.

At risk of falling below the minimum buffer zone are Ayala Land Inc. (ALI) and PLDT (TEL), to mention two prominent issues. In the case of ALI, it has faced recent selling pressure dragging it down. If ALI’s free-float values drop near or below the P76.0 billion floor (two-thirds of the standard free-float entry requirement), it may soon face the same migration track JFC previously did. 

Because MSCI evaluates index participants through a “buffer zone” framework, neither stock faces an immediate, unannounced deletion. However, because both companies have drifted to the absolute bottom limits of the large/mid-cap boundary, global fund managers are actively monitoring their valuations.

The squeeze in their prices and volume of transactions is said to be due to poor financial performance and condition which were sounded last June 2026.  

Following the actual demotion of JFC in May 2026, ALI and PLDT are the next two premier blue-chip stocks expected to face the inevitable fate of a downgrade. The wait is not too far away. On Wednesday, August 12, MSCI will announce the result of its rebalancing and index reviews.  

Abangan. (Watch out for it.) – Rappler.com

(The article has been prepared for general circulation for the reading public and must not be construed as an offer, or solicitation of an offer to buy or sell any securities or financial instruments whether referred to herein or otherwise.  Moreover, the public should be aware that the writer or any investing parties mentioned in the column may have a conflict of interest that could affect the objectivity of their reported or mentioned investment activity. You may reach the writer at densomera@yahoo.com)  

Below are a couple of columns of the author on the stock market you may have missed:

Similar Posts

  • | | |

    PSX ends week lower as KSE-100 loses 4,781 points

    The Pakistan Stock Exchange (PSX) closed the trading week with a significant decline, as the benchmark KSE-100 Index recorded heavy losses amid continued market volatility. The negative trend reflected cautious investor sentiment and sustained selling pressure across several sectors. During the week, the KSE-100 Index fell by 4,781 points to close at 171,021 points. The decline marked a weak performance for the stock market after several volatile trading sessions. Investors remained cautious throughout the week, resulting in fluctuations in share prices. The market witnessed wide swings during the five trading days. The benchmark index moved within a range of 8,857 points. It touched a weekly high of 178,370 points before dropping to a weekly low of 169,512 points, highlighting the uncertainty that dominated market activity. Despite the fall in the benchmark index, trading volumes remained healthy. Investors traded a total of 3.48 billion shares during the week. The combined value of these transactions reached Rs138 billion, indicating that market participation remained active despite the downward trend. The market decline also affected the overall value of listed companies. The total market capitalisation of the Pakistan Stock Exchange dropped by Rs512 billion during the week. As a result, the market’s total value stood at Rs19.278 trillion at the close of trading. Market analysts said investors adopted a cautious approach due to uncertainty surrounding economic conditions and profit-taking after recent gains. Selling pressure in key sectors also contributed to the decline in the benchmark index. Experts believe investors will continue to closely monitor economic indicators, corporate earnings, monetary policy developments and government decisions that could influence market sentiment in the coming weeks. Any positive economic developments or improved investor confidence may help the market recover, while continued uncertainty could keep volatility elevated. The week’s performance underscores the sensitivity of the Pakistan Stock Exchange to economic and financial developments, with investors expected to remain watchful as the new trading week begins.

  • | | |

    PM forms top panel to revive Iran gas pipeline

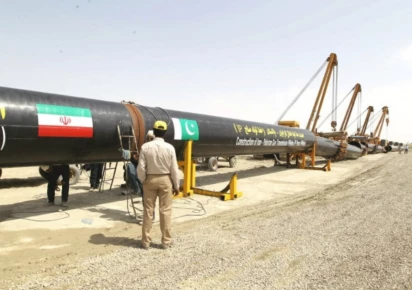
    Prime Minister Shehbaz Sharif has formed a high-level committee to find a mutually acceptable solution to the long-delayed Pakistan-Iran gas pipeline project, which has remained stuck for more than a decade. Petroleum Minister Ali Pervaiz Malik informed the Senate that the committee is examining the legal, financial and energy implications of the project. It will assess Pakistan’s potential financial exposure in the ongoing arbitration process while also considering the country’s future energy requirements. The minister was responding to a calling-attention notice raised by Senator Talha Mahmood. He said the government was seeking a negotiated solution rather than allowing the dispute to become more complicated through prolonged litigation. Describing Iran as a “brotherly country”, Malik said the leadership of Pakistan and Iran remained in contact and was working towards an amicable settlement. He noted that Iran had already completed substantial infrastructure on its side of the project. Iranian authorities have brought gas from the South Pars field towards a major city close to the Pakistani border. The dispute over the pipeline has reached international arbitration in Paris. Pakistan is therefore assessing the possible financial consequences of the project delays and the legal proceedings before deciding its next course of action. The government is also reviewing whether the pipeline can be made commercially viable. Pakistan has previously asked Iran to cut its gas price by around 50 per cent and reduce the proposed supply volume because several domestic sectors have shown limited interest in purchasing Iranian gas at existing prices. Officials have said that domestic consumers and fertiliser plants are currently receiving gas at significantly lower prices than the cost at which imported gas could be supplied through the project. Power producers have also indicated that purchasing imported gas at prices above Rs2,000 per million British thermal units would not be commercially feasible. The government has therefore been considering a lower price as a potential benchmark for making the pipeline economically sustainable. Pakistan has also indicated that it could move ahead with the project if the United States provides a waiver allowing energy cooperation with Iran despite Washington’s sanctions regime. The Iran-Pakistan pipeline, commonly known as the Peace Pipeline, was originally designed to transport Iranian natural gas to Pakistan and help address the country’s long-term energy needs. Iran completed a substantial portion of the pipeline within its territory. Pakistan, however, did not complete its section by the agreed deadline, leaving the project largely dormant. US sanctions against Iran, difficulties in securing financing and wider geopolitical tensions have complicated Pakistan’s efforts to complete the project. The issue has also resulted in legal disputes between the two countries. Iran initiated international arbitration proceedings in Paris over delays in the implementation of the project. Meanwhile, the petroleum minister told the Senate that the government was separately addressing gas-related problems in Balochistan. He said Prime Minister Shehbaz Sharif had instructed him to engage with provincial stakeholders. Another high-level committee, headed by Deputy Prime Minister and Foreign Minister Ishaq Dar, is examining gas-related issues in the province, including technical and payment-related matters. The latest move indicates that Islamabad is attempting to balance its obligations under the Iran gas project with its financial constraints, international commitments and changing energy requirements.

  • | | | | | |

    Ramon Ang buys his way into Lopez Inc., which owns what he already builds

    So far, what has actually changed hands is one family branch’s stake in the private company at the very top of the Lopez empire. Whether it leads to a direct ABS-CBN rescue is a question about what Ang, and the Lopez family, do next.

  • |

    Bank of Punjab Board approves Up to Rs30bn equity injection by Punjab government

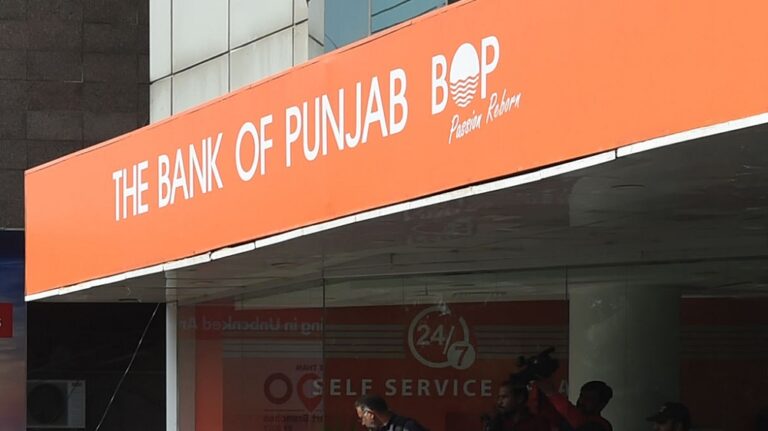
    LAHORE: The Board of Directors of The Bank of Punjab (BOP) has approved a proposal for an equity injection of up to Rs30 billion by the Government of Punjab, a move aimed at strengthening the bank’s capital position and supporting its next phase of expansion. The decision was taken at a board meeting held on August 7, 2026. Under the proposal, the Punjab government will subscribe to ordinary shares to be issued by the bank through a mechanism other than a rights issue. The proposed transaction will not take effect immediately and remains conditional on obtaining all required statutory, corporate, shareholder and regulatory approvals. According to the bank, the planned capital injection is an important step in its broader transformation strategy and will provide additional financial capacity to support sustainable growth across its key business segments. Share issuance price The ordinary shares will initially be issued at Rs38.20 per share. However, if the market price of BOP shares is higher than this amount at the time of issuance, the shares will be issued at the prevailing market price plus a premium of 5 percent. As a result, Rs38.20 will serve as the minimum or floor price for the proposed share issuance. The transaction is expected to reinforce the bank’s capital base and provide greater flexibility to manage balance-sheet expansion while maintaining prudent financial and risk-management standards. BOP expands its market presence The Bank of Punjab has undergone significant changes in recent years, with the institution expanding its balance sheet, improving financial performance and strengthening its position across several sectors of Pakistan’s economy. The bank has developed a strong presence in areas including small and medium-sized enterprise (SME) financing, agricultural lending, affordable housing, digital banking and credit cards. It has also increased its focus on women’s participation and leadership in banking and financial services. BOP is further expanding its activities in commercial and corporate banking, particularly in areas linked to export-oriented businesses. The bank said these business segments have positioned it as an important participant in supporting economic activity, employment creation and financial inclusion across the country. Capital requirements rise with expansion Despite the bank’s growth, the rapid expansion of its operations has increased pressure on its existing capital base. BOP said its capital position has historically remained relatively limited compared with the size of its operations and the growth opportunities available to the institution. The proposed Rs30 billion injection is therefore expected to provide the bank with additional capacity to expand its core businesses while maintaining financial resilience. The additional capital could also enable BOP to increase its low-cost deposit base and grow lending operations without facing the same level of capital constraints. The bank said strengthening its capital position would allow it to pursue growth while maintaining a balanced and prudent approach to balance-sheet management. Strong financial performance The proposed capital injection comes as BOP continues to report strong underlying financial performance. During 2025, the bank recorded revenue growth of around 29 percent, while its earnings increased by more than 40 percent year on year. The bank also witnessed significant appreciation in the value of its shares during the period. According to the bank, the proposed capital raise should therefore be viewed primarily as growth capital rather than a measure aimed at addressing immediate financial weakness. The additional equity is expected to provide the financial foundation required for BOP to continue expanding its operations and investing in new business opportunities. International expansion in focus Another important component of the bank’s future strategy is its international expansion. The capital injection is expected to support the next phase of BOP’s growth, including an international venture that has recently received approval from the State Bank of Pakistan. The move could provide the bank with an opportunity to broaden its geographical footprint and develop new sources of business and revenue. With the proposed equity injection, BOP aims to strengthen its financial position, support expansion in priority sectors and improve its ability to serve businesses, consumers and other customers as demand for banking and financial services continues to grow.

Leave a Reply

Your email address will not be published. Required fields are marked *