[Vantage Point] Oil’s false prophets
The Economist mocked investors in late April for predicting Brent crude oil to reach roughly US$88 per barrel by the end of the year.
Brent Crude—a light, sweet crude oil originally extracted from the North Sea—is widely used as the primary international benchmark for pricing oil globally because its properties make it easy to refine into high-demand products like gasoline and diesel. On July 2, however, the publication issued a retraction as spot Brent prices plummeted to slightly over $70.
That mea culpa looked sincere, but it committed a new forecasting mistake. It compared oil for delivery at year-end with a single day’s price in July, erroneously treating the difference as a verdict on a war and a timeline that have yet to conclude.
A December futures contract and a July spot Brent answer different questions. While spot measures an immediately available barrel, a year-end contract reflects expected supply, demand, inventories, storage costs, interest rates, and geopolitical risk months ahead.
The valid test was not whether spot stood below $88 on July 2, but how that December contract had moved since April and where it eventually settled. Brent surged toward $100 as attacks against tankers and threats to the Strait of Hormuz and Bab el-Mandeb returned, making the apology another attempt to call the ending before the final act.
The two maritime straits are the world’s most critical chokepoints, handling a combined total of over 20 million barrels of oil daily and a significant percentage of global container trade. Recent blockades due to the ongoing conflict between the United States and Iran have severely disrupted these global energy and commercial shipping corridors.
Oil forecasting in wartime fails because analysts confuse three quantities: gross supply disruption, net market deficit, and quoted price. During March, April and May, flows averaged only 2.7 million, implying a 17.3-million-barrel reduction in daily traffic.
Global production fell 10.1 million barrels a day in March. By May, it stood 13.6 million below its prewar level. The International Energy Agency (IEA) was not exaggerating when it called this the largest physical oil disruption in history.
Losing 13.6 million barrels of production, however, does not create an equal market deficit. The balance is production plus inventory releases, minus consumption and stockbuilding.
In the second quarter, global demand fell by almost 5 million barrels a day year on year. IEA countries authorized 400 million barrels from emergency reserves, while observed inventories declined at an average 3.8 million barrels daily after hostilities began. Atlantic Basin exports redirected toward Asia rose by 3.5 million barrels a day. These responses did not erase the loss; they prevented its full force from appearing in spot Brent.
China ‘saves the world’?
Although China supplied a separate adjustment, saying that Beijing “saved the world” confuses a drop in demand with actual production. Chinese imports dropped from a five-year average of 11.5 million barrels a day to about 8 million during the crisis, then plunged to 7.12 million in June—the lowest since 2016.
China and Japan together cut imports by nearly 6 million barrels daily as refinery runs and industrial consumption weakened. Those absent Chinese bids released cargoes for other buyers, but no additional oil was manufactured.
This is where linear forecasts collapse. Analysts estimate how much supply is lost and apply an assumed price response, but neither side remains stable. A closure may stop tankers without destroying production; producers store oil until tanks fill, after which output must be shut. Consumers drive less, delay flights, switch fuels, or accept slower growth.
Governments release reserves, suspend taxes, and subsidize transport. Every price increase alters the demand it measures, making oil a feedback system rather than static arithmetic.
Opacity compounds the problem. Nobody outside Beijing can measure China’s strategic stocks or predict when officials will replenish them. Spare production is counted even when the barrels sit behind a blocked strait. Announced pipeline capacity is confused with usable capacity: Saudi Arabia and the United Arab Emirates had about 2.6 million barrels a day of spare bypass capacity before the crisis, which is a fraction of normal Hormuz traffic. Politics is less tractable still. A ceasefire can remove $20 of risk premium; one tanker attack can restore it overnight.
Brent can give false comfort. Motorists buy refined fuel, not crude, and their bill includes refinery margins, freight, war-risk insurance, currencies, taxes, and inventory timing. During the crisis, crude weakened, while diesel and gasoline remained scarce. Refining margins exceeded $60 a barrel, while Asian refined-product imports remained below prewar levels.
Moderate Brent could thus coexist with punishing Philippine diesel prices. Anyone watching crude alone was measuring the input, while missing the damaged machinery converting it into fuel.
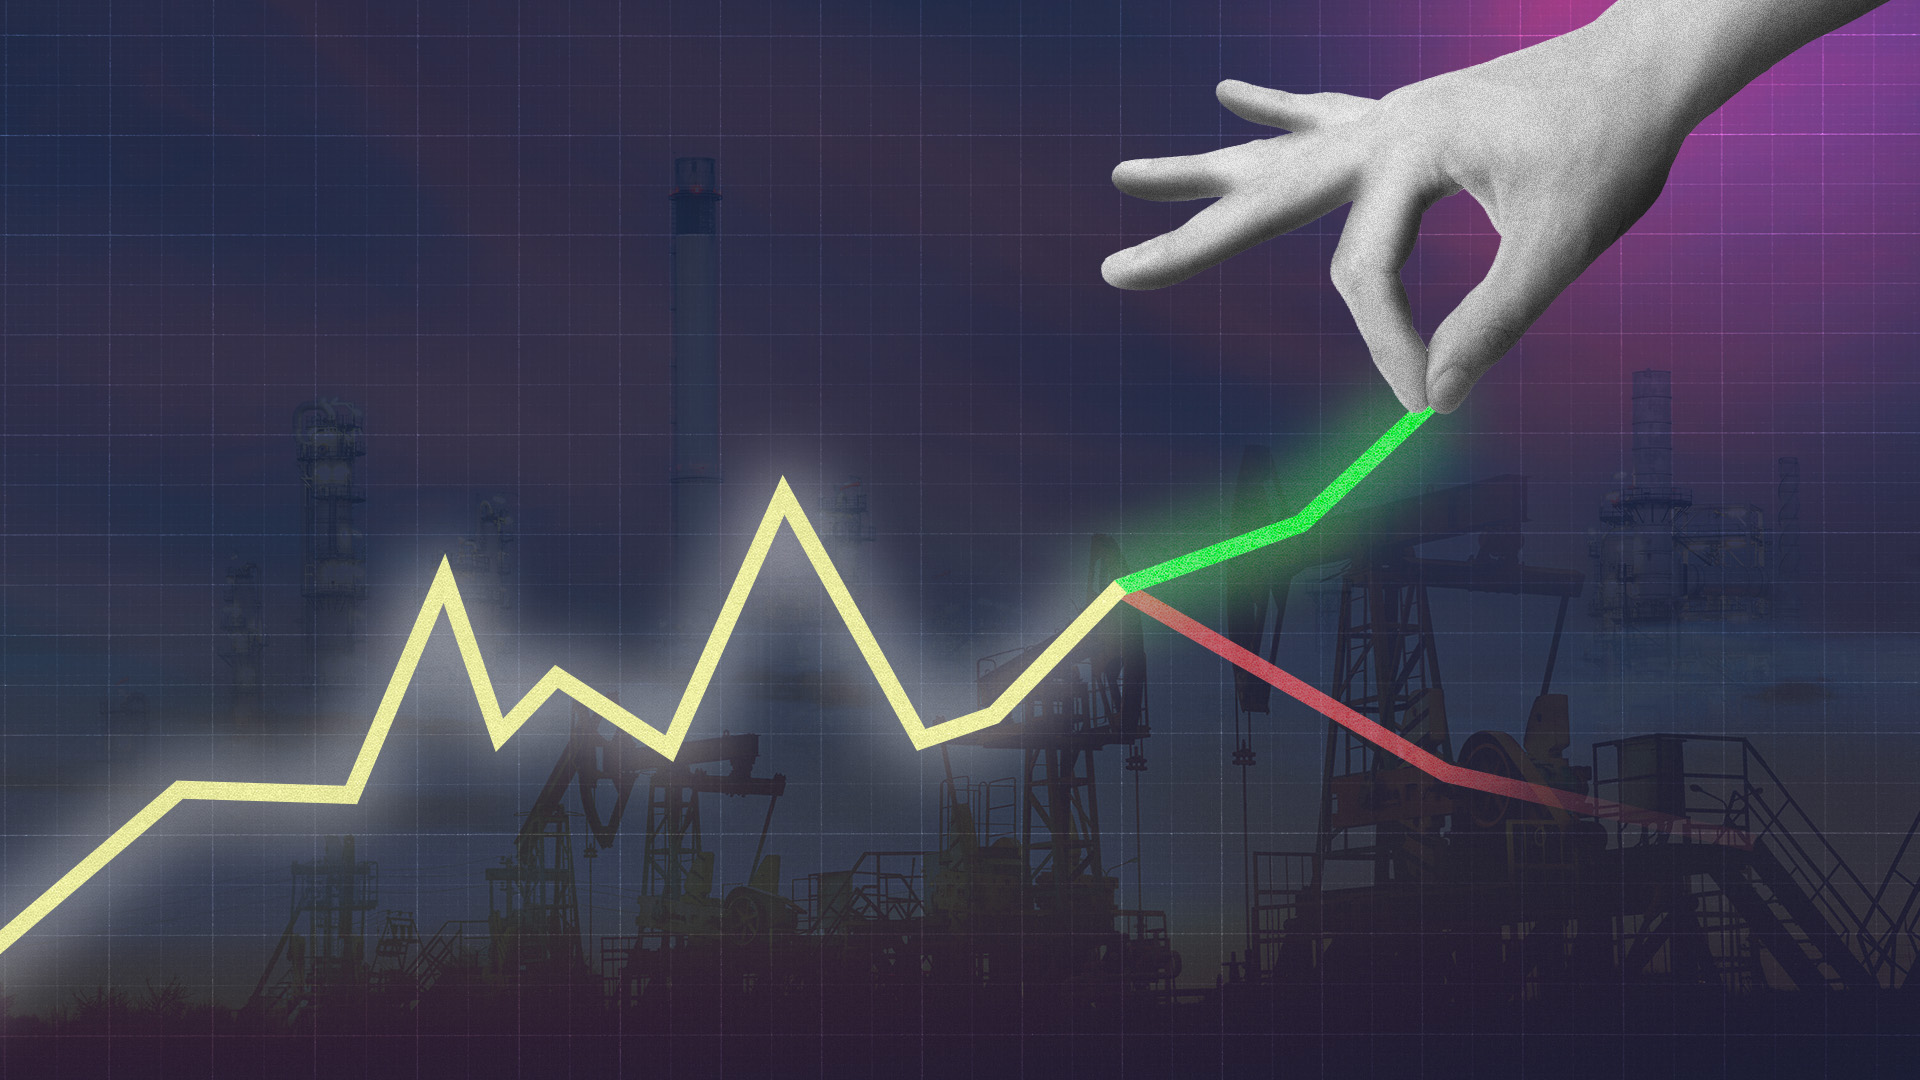
The honest method is scenario analysis, not theatrical precision. A durable reopening of Hormuz may return Brent toward $70 to $80; intermittent disruption combined with Chinese restocking can support $90 to $110; simultaneous restrictions at Hormuz and Bab el-Mandeb can make $120 plausible.
These are conditional ranges, not prophecies. These are conditional figures that must be adjusted as key factors shift. These factors include transit volumes, inventory releases, Chinese import levels, consumer demand drop-offs, and overall geopolitical conflict duration.
The Economist deserves credit for admitting error, but its deeper mistake was believing that one price snapshot could settle the argument. The shock was real: more than 1.3 billion barrels of cumulative Middle East supply were lost, while inventories and emergency reserves absorbed the damage.
The world was not rescued from scarcity; it borrowed barrels from the past, suppressed present demand, and reduced its insurance against the future. Forecasting fails when analysts mistake temporary resilience for abundance—and forget that in wartime, the crucial number is not today’s price, but how many cushions remain when tomorrow’s disruption arrives. – Rappler.com
This analysis draws on oil-market data from the International Energy Agency, including its March, April, and June 2026 reports and its assessment of the Strait of Hormuz disruption; the US Energy Information Administration’s estimates of normal Hormuz traffic and available Saudi and UAE bypass capacity; and Reuters reports on Brent prices, China’s crude imports, global refining margins, and Asia’s refined-product shortage.
The projected Brent ranges of $70–$80, $90–$110 and $120 or higher are my own scenario estimates, not forecasts issued by these institutions, and depend on the duration of the conflict, Hormuz transit volumes, Chinese restocking, inventory depletion, and any simultaneous disruption at Bab el-Mandeb.
Below are other Vantage Point articles you may have missed:
Click here for other Vantage Point articles.